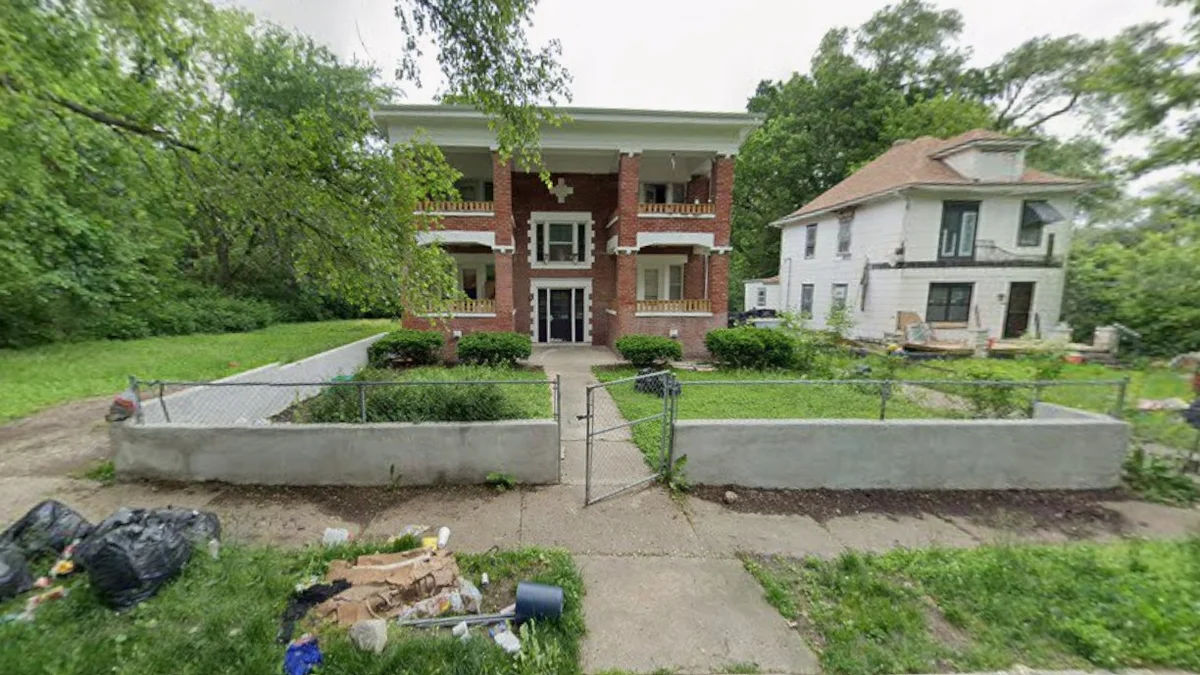
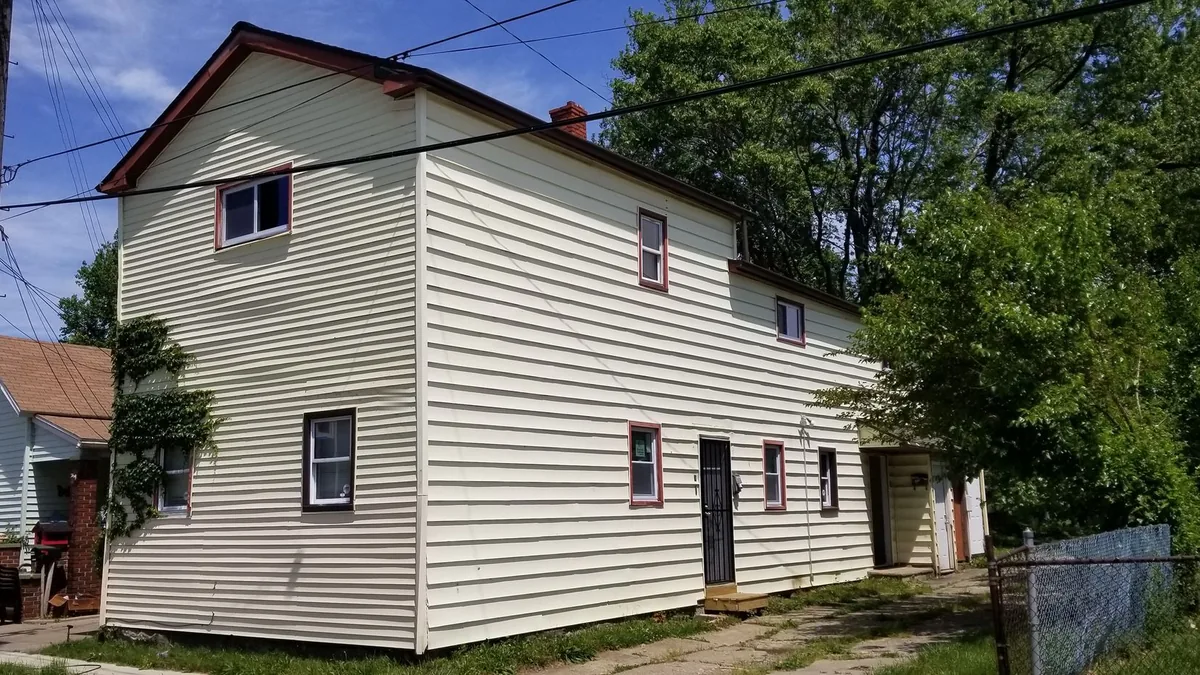
There are four 3-bed, 1-bath apartments, "recently renovated" (although based on the listing pictures I'd say minimally), each with its own central air. One unit is let at $1,600 a month. The listing multiplies that by four and calls it $76,800 a year. But that's spreadsheet income, not real life bank account income.
After running my review and analysis I told my client to pass because it failed hard on both location and numbers. Here's the math, and the three things the listing leaves out that will lose you money in the real world.
The numbers as offered
| Item | Listing |
|---|
| Price | $450,000, about $112,500 a unit |
| Units | 4, each 3 bed / 1 bath |
| Size | About 3,960 sq ft, full basement |
| Built | 1910, brick |
| Occupancy | 1 of 4 let, at $1,600 a month; the other 3 "expected to be leased to voucher tenants" |
| Rent claimed | 4 × $1,600 = $6,400 a month, $76,800 a year |
| Gross yield claimed | $76,800 ÷ $450,000 = 17.1% |
| Utilities | Tenants pay everything except water |
| Property tax | $2,626.50 (2026 bill, county record) |
Financed with a foreign national DSCR loan at 70% LTV with an 8% interest rate (live updates on my DSCR loan rates for U.S. citizens and foreign nationals), the loan is $315,000 and the payment is $2,311 a month. That's a debt service load of $27,736 a year. The down payment would be $135,000, plus about 5% closing, so $157,500 total. I'd also highly recommend holding at least $20,000 in liquid reserves from day one for a property like this.
On the listing's current and projected rent, with property management at 10% and nothing else set aside, this property looks superb:
| Line | Listing, a year |
|---|
| Gross income, 4 × $1,600 × 12 | $76,800 |
| Management, 10% | −$7,680 |
| Property tax | −$2,627 |
| Insurance | −$3,000 |
| Water, landlord-paid | −$3,600 |
| Net operating income | $59,893 |
| Mortgage, 8%, 30 years | −$27,736 |
| Cash flow | $32,157 |
| Cash-on-cash, $32,157 ÷ $157,500 | 20.4% |
If you want to test that yourself, my cash flow calculator takes the same inputs.
What looked good
The location line in the listing isn't wrong. The building is about two miles from downtown, with the hospital campuses, Crown Center and Midtown within a short drive.
Our neighborhood analysis report showed jobs within five miles are up 14.5% in ten years, most of it in health care. A new grocery store opened at the end of the street in May, and the Prospect bus rapid transit line runs a block away.
Rents in the ZIP are rising too. HUD's rent limit for a 3-bed here went up 14% this year. And a 4-plex of 3-beds is the right shape for families who stay, if the rest of it works.
Unfortunately, it doesn't.
The number that killed it
Two numbers, really: the rent and the maintenance. Both of these are, in my opinion, off by some considerable margin.
The rent. $1,600 is what one unit is let for. But it isn't what the market pays. When I ran rental comps I saw the 3-beds for rent around it asking $1,375 to $1,450, including a 3/1 apartment on the next block at $1,400. So $1,600/mo is way above market in a neighborhood where a lot of tenants are already financially constrained, for a property that attracts the lowest income bracket of that pool.
The listing does get one thing right: "perfectly suited for the housing voucher rental market". I agree. This is the kind of property that is most suitable for a housing choice voucher (Section 8) tenant. Not many high quality private tenants want to live in a 4-plex in a high crime neighborhood, and if they do, they probably won't stay long. So the real question is what each unit would rent for to a voucher tenant, and the answer is less than $1,600 on most of these units.
HUD's FY2027 limit for a 3-bed in this ZIP is $1,620, and the Kansas City housing authority pays up to 110% of it. That limit is gross: it includes utilities. Here the tenant pays every utility except water, so the authority deducts a utility allowance before it gets to the rent. And before it approves any rent at all, it has to find it reasonable against comparable unassisted units, which on these streets are at $1,400. Fair Market Rent isn't the rent you'll get, and this is exactly the gap that article is about. One unit at $1,600 is a lease. Four at $1,600 is a hope.
The maintenance. The building is 116 years old, and the interior photos don't look like a recent renovation. Also, my experience of housing this end of the tenant pool tells me your maintenance bills are going to be higher than average. At this end of the market, you can expect problems.
The city's permit records don't show a recent renovation either. There's a 2022 electrical service upgrade and some gas-line work this year, but no roofing permit and no mechanical permit, though the listing claims a new roof and central air in every unit. A permit for the main drain stack was canceled the day after it was applied for, with no inspection. There was also a fire in April, investigated by the city, and no building permit for the repair.
So I underwrote it the way I'd own and manage it: voucher tenants, because private tenants on this street would turn over constantly; 5% vacancy, because voucher tenants stay; $20,000 a year for maintenance across four old apartments; and 10% management, because Section 8 inspections cost a manager time.
| Line | Listing | My underwriting |
|---|
| Rent | 4 × $1,600, $76,800 | 4 × $1,400, $67,200 |
| Vacancy | $0 | 5%, $3,360 |
| Maintenance and repairs | $0 | $20,000 |
| Management | 10%, $7,680 | 10%, $6,720 |
| Property tax | $2,627 | $2,627 |
| Insurance | $3,000 | $3,000 (estimate) |
| Water, landlord-paid | $3,600 | $3,600 (estimate) |
| Net operating income | $59,893 | $27,893 |
| Mortgage, 8%, 30 years | $27,736 | $27,736 |
| Cash flow | $32,157 a year | $157 a year |
| Cash-on-cash on $157,500 | 20.4% | 0.1% |
That's $13 a month on $157,500, before anything goes wrong. And three things on this building are likely to.
What else is waiting
Three empty units. You'd be buying at 25% occupancy, and paying for three lease-ups, three voucher inspections and three sets of make-ready on day one, in a census tract where a quarter of the homes are empty.
The tax bill. The county's payment history shows the bill rising from $1,900 in 2021 to $2,627 in 2026. It also shows two payments of about $12,700, in 2023 and 2024, each reversed the same day. I can't tell from the record whether that was a misapplied payment or a bill at a higher value that was later corrected. But $12,700 is roughly what a bill on a $450,000 to $500,000 value looks like here, and Jackson County reassesses in 2027. If the county moves this building toward its sale price, the cash flow above goes to about −$9,200 a year. The tax on the listing is usually the previous owner's bill, not yours.
The street. I graded the neighborhood before I looked at the rent, as I always do. It scored 36.6 out of 100 on my grading, Phase 1, one of the 29 Kansas City tracts I'd avoid. Crime reports within a quarter mile are on pace to finish 65% above 2022 and 38% above last year, while the city's are falling. There have been two homicides within a quarter mile this year. The block itself is quiet; the circle around it isn't. Three houses on the street directly behind have open dangerous-building cases, all opened this year.
Any one of those would have been a condition. Together, with the rent and the maintenance, they're a pass.
What would have changed my mind
Personally, I wouldn't buy this at any price. I know first hand the difficulties of owning and managing real estate at this end of the market, and I'm not going there again.
If one was so inclined to own cheap government subsidized housing, the main lever to pull would be the price. At my underwriting it returns 8% on the cash in at about $310,000, $140,000 under asking.
At that price I'd still want three things before I made an offer: the county's answer on the reversed tax payments, permits or invoices for the roof and the four air conditioning systems, and a voucher rent approval from the housing authority on one of the empty units, not an expectation.
The bottom line? This is a listing written for an investor who'll do the multiplication and stop. $1,600 × 4 × 12 is $76,800. What the building will actually pay you is $157 a year, and that's if the tax bill stays where it is. Cash flow isn't your profit, and on this one there isn't much cash flow either.
I passed on a Cleveland triplex for similar reasons last week. Both looked like 10% to 20% deals on the seller's sheet. Both came out at zero once the real costs were in.
Every week, one property that came through my seller network or a client's inbox, looked right on paper, and failed due diligence. If you want the same checks run on something you're looking at, send me the address.